
Too late for me to say ‘Happy New Year’ but I hope everyone had a good one.
Apologies for the lateness of this post but going back to work was a shock to the system so I’ve been very reluctant to face my laptop outside of work hours. It’s getting worse with each passing year.
Anyway, let’s just get the numbers out of the way for 2025!

I saved 25.2% of my net salary. The above included £14.38 I received from doing Prolific surveys.
Shares and Investment Trusts
No new investments, I just topped up existing ones.
Current share/IT portfolio can be found here.
(Entire portfolio here)
Future Fund
Santa continued to be overly generous and as at 31st December 2025, my Future Fund stood at £368,632.98. That’s a 25.7% increase from this time last year (that’s 25.7% including money I’ve added as well as investment gains). I had thought 2024 was a good year, did not see this at all for 2025.
Here’s how it all looks at the end of what appears to have been an incredible year:
 My investments have completely ignored the doom and gloom of news, world events and politics and blissfully continues on an upward trajectory. Long may this continue! For how long, who knows?
Using unitization, I am up by 18.1% across my entire portfolio – that’s investments, cash, premium bonds, dividend income portfolio, everything I own.
I’m sure other investors can boast about much bigger gains and good for them, but I am so happy for me that I’ve got these gains – I’m not competing against anyone or any benchmark – I did better than last year (10.3%) so go me!
What’s in store for 2026? It seems to have begun on a high but I’m just really wary right now of bubbles, just can’t shake off the uneasy feeling that we’re moving up a cliff and the edge may not be avoided…
Dividends and Other Income
A decent final month for dividends:

I received £606.65, of which £277.86 was from my ISAs, the rest from my SIPPs.
I had already smashed my income goal of £4.6k last month and ended the year on £5,094.49 in total. Here’s how the income was spread over the year:
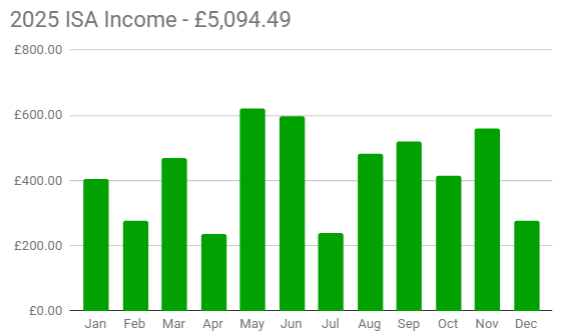
Average yield was 5.4% / 6.2% on value / cost.
Goals Update
And here’s how it all ended:

Three achieved which isn’t bad. Not really too worried about the two I failed – I must have had fewer friends doing running events for me to sponsor for charity and for emergency funds, I think I made progress so this will definitely be achieved in 2026 (finally not going to set as a goal).
I read a total of 20 books (my Goodreads goal) this year. The non-fiction/classic goal seems to work for me, encouraging and pushing me to read books outside of usual reading comfort zone. I’m glad I was able to read so many books off my bookshelves, but there are still many more to go so that will likely be another goal again.
The last non-fiction book I read? ‘The Princess Diarist’ by Carrie Fisher.
Already mentioned my ISA dividend income – this is now over and above my original goal of average £400 per month to cover most of my basic household expenses (council tax, broadband, gas and electricity and my monthly grocery food bill), so am well chuffed I blitzed this goal.
What’s another Year?
2025 was a decent year. I’ve been mostly healthy in mind and body, occasionally mentally exhausted at times but no real injuries or illnesses.
Still going through the motions of the peri-menopause and it got to the point end of last year that I finally reached out to the doctor and have been prescribed HRT to ease symptoms. And yes, I do feel better.
Another year at work – same old grind, yet I feel like we have made progress on things we (me and the boss) set out to achieve, so that feels good. However, now that I have set a date of sorts for my FIRE, my toleration for BS continues to wear away a sliver at a time.
My social life has been as much as I’ve wanted it to be, I’ve enjoyed outings with friends, attended most of the Manchester FIRE meet ups, attended WI meetings, had a trip to London to see the NFL American football, and enjoyed a lovely trip to Hong Kong and Singapore to see my family.
Another year of making my own kefir – those grains I bought years ago are still going strong! I don’t have my smoothie every day, probably 3-4 days a week but I think my gut health is pretty good.
New Year, New Challenges?
New year, still same old me.
As usual, when the thought turned to goals, I couldn’t really think of anything which I should be doing or doing more of, which could be set as a goal or NY resolution.
I think I need to just keep things ticking along, keep my costs down where I can (my grocery shopping needs to be looked at), enjoy my life and while I do need to think about what FIRE will hold for me, I need to not stress over it!
So no radical goals, unless something pops in my head this week but really they will be the usual ones which will keep me focused and ones I can keep to.
Anyway, here’s to a happy, healthy and hopefully wealthy 2026 to all of us!
Nice work on completing the ‘Couch to £5k ISA Divi Challenge’. It’s really rewarding to hit these little personal milestones….then of course set another reachable target to maintain the focus for the next year or two. Also, well done on the 18.1% portfolio growth for 2025. My overall portfolio performance is more in line with Monevator’s Slow And Steady (ie circa +11.5%), but I’m more than happy with that as i’m a bit more defensive these days.
It’s been emotional following the precious metals market for the last few months – i can’t quite believe what i’m seeing, but there has to be some major fallout at some point….Questions are…What exactly? And when? I’m getting increasingly concerned about the paper silver ETF’s, possibly a ‘force majeure’ situation, where the deals get ripped up and investors get back pennies in the pound??? Note to self – do not get greedy! Anyway, the Hollywood film should be great when they get round to making it.
Good to hear you’re still on the kefir. It’s been part of my daily routine now for a few years and long may it continue. There’s so much positive commentary about it and yet it seems so few in the western world have switched on to it.
PS – i didn’t get the chance to reply to one of your prior posts that made reference to accessing the DB pension. I was just going to say make sure that you look into the adjustment factors that typically apply both in a negative way when accessing early, and in a positive way when delaying access past the normal retirement age. Some schemes can have quite generous uplift factors if the member opts to delay by a year or two, so i would just say make sure you investigate these before pulling the trigger. For me, i want the ‘floor income’ to be as much as possible, but obviously everyones circumstances are unique.
And belated HNY.
Hi KC
Totally agree on the emotional aspect of following the markets – I should be happy that my investments are booming yet I’m not as I’m waiting for a major fallout at some point. Happiness tinged with dread, haha!
Yes, still loving my kefir – my sister started making kombucha which is ok but I’ll stick to what I know!
In respect of my DB, I’ve only requested a quote thus far of when I access it on my 65th birthday. I have yet to see what the real difference is if I were to access a year (maybe 2) earlier, or a year later, though the latter would be unlikely as my plan needs me to access it at 65. I just recall that earlier, the reduction was pretty big so would be interesting to see what the actual difference was.
Anyway, belated HNY!
Your 18.1% increase in unit value makes you leader of the pack, so far. My unit value increased by 13.9%. I’d assume this is mostly because in the last quarter I decreased my equities leaving my portfolio at around 50% equities, 50% bonds/cash. Yes, I’m getting nervous about these equity values.
I looked at your portfolio just now, and I note that you have 30% in defensive assets (bonds/gold). Given that you’re planning to exit planet work next year, are you going to be more defensive soon?
Hi Curlew
13.9% is excellent considering your decrease in equities. I too am a little nervous, yet wanting to continue to ride on the gains so I’ll just continue to shift some a bit at a time to defensive.
That 30% might end up 40%, I’m not sure if I would go to 50%. That might depend on how much cash I have for safety. Nothing is set in stone of course, my view and sentiment will change depending on what happens in the market.
Hi Weenie,
Long time subscriber but first time commenter 🙂
Thank you for your blogs, really inspirational as I’m a fair bit behind you!
I just wanted to ask about Matched Betting, as I think you used to do it but I don’t see any updates recently? Have you stopped doing it and if you don’t mind me asking, why you have stopped? I was thinking of starting it this year as another source of income but not sure how much time it would take as I work full time as it is. Thanks for any insight you can give!
Hey San
Yes, I used to do matched betting but I stopped for a couple of reasons. The first being that bookies don’t like you taking money off them so I got restricted from all (and I mean ALL) the main big bookies, so I was unable to take advantage of free bet bonuses. The second was time – it is very time consuming -more time spent = more profits. Although I did most of my matched betting during weekends and as I only had smaller bookie accounts, the smaller bet bonuses and offers meant a lot more time and effort was needed to make any decent profit.
However, I still do practise some of the MB ‘skills’ I learned. I occasionally place sporting bets and will use my exchange account to lay bets to reduce any losses. I think this has enabled me to keep a balance going in my active betting account without having to top it up for a couple of years!
I do think once you’ve researched, it’s worth giving MB a try to see if it’s something you like to do/have time to do. There is still money to be made but know that while it is straight forward, it is not easy to make big profits.
Good luck if you do try it, and thanks for reading and commenting!