
[edit – sorry, didn’t realise comments turned off, they’re on now!]
[edit – off again]
I have been so busy just going about my everyday business, that not only did I forget my blog anniversary earlier this year but I completely skipped last year’s anniversary! Must have been menopausal brain fog! Oh well!
Happy belated 12th birthday to Quietly Saving! 🙂
 Anyway, wow, long time or what!
My blog is ancient! Old school and retro? I’m fine with that! It works for me – so many (far glossier and modern) FIRE blogs have fallen by the wayside over the years, disappearing into the internet abyss. Sadly, I’ve not had the time (yet) to seek out new ones to add to my redundant blog list. Think the young people aiming for FIRE prefer vlogs.
Last Woman Standing
Do I still enjoy writing this blog? Yes, I still find it freeing to be able to write like this. The blog helps me focus, documents my journey, helps motivate me, it’s a place to empty some of the thoughts rattling around my head or to articulate ideas. It also keeps me accountable.
Some might describe my progress over the years as ‘plodding’ but the truth is, I’ve just gone as fast I’ve wanted to; I was never in a rush to FIRE and I’ve not suffered from FIRE burnout, have just steadily and purposefully moved forwards at my own comfortable pace, step by step. It’s my race, not anyone else’s.
And now here I am, on the final leg of my journey, having set a FIRE date of 2027! I will do an update post on that as it’s been 10 months (already!) since I made that announcement.
My mindset about FIRE has shifted because it finally really isn’t that long now, yet I have to admit that my mind is still resisting a little about making that next mental step, which is diving into the detailed particulars of decumulation…
Don’t worry, I will get my head round this, I do have a plan of sorts.
Humdrum
Gosh, so all this time, I’ve been posting my rather unexciting numbers monthly (with some glimpses of my life) for 12 years!
There’s nothing extravagant about my relatively ‘ordinary’ life; it’s one which is filled with a lot of mundane, routine, same-old-same-old stuff, with good things far outweighing the bad. I’m an optimist so that’s how I see it.
What have I been doing these past 12 years?
I’ve just been living my life, which still pretty much boils down to work, gym, eat and sleep.
I have mostly enjoyed a good work/life balance, although there are times when work encroaches on my gym time but generally, I have spare time to read (books), play video games, watch tv, socialise with friends and family, and gardening in the summer. I attend sports events when I can (eg Wimbledon, NFL and Women’s World Cup Rugby was the newest one). Travelling and holidays is usually just one big trip away each year to see my family in Hong Kong.
I have been fortunate that my adult life has been relatively free of ‘drama’ which continues to be mostly in my control, am very conscious of looking after my health especially now that I am ‘middle-aged’ (“everything in moderation” is still my motto). There is nothing of any note, aside from the breakdown of a long-term relationship (15 years), being made redundant at the end of 2016 from the company where I’d enjoyed a 21-year career, my sister and nephew moving in to live with me for a year or so, my BTL getting caught up in the cladding shenanigans (still not resolved) and then me buying a home during a peak property period.
I have been quite content with my life these past twelve years, there’s nothing really that I want to currently improve. Some more strength and flexibility perhaps?
My general health is good, physical and mental and I continue to make an effort with both. HRT has made me feel more like ‘me’ than I have done in recent years and relieved symptoms I was just putting up with, and despite some stress over a bad eczema flare-up earlier this year, there’s nothing else for me to complain about.
The increase in costs of living concerned me a little and I had to revise my FIRE goals to adjust but I think it’s mostly accounted for now in my numbers.
Over the last 12 years, I’ve aimed to save/invest as much of my net salary as possible – there was a time when I was able to save 40% of my net salary, even managing over 50% during the pandemic.
I’ve invested in mostly global index trackers but around 25% of my total portfolio is dedicated to paying dividend income. Not all my investments have been successful – I’ve gotten distracted by P2P and crowdfunding but never in a major way, so no harm done.
I continue to put money aside for my ‘house fund’ and am also overpaying the mortgage. I won’t be mortgage-free when I FIRE but that was always part of my plan.
I am aware of how lucky I am that I am not struggling with a cost of living crisis and am aware that I’m in a bit of a bubble with my friends and family who are all in a similar situation of being to able to live without financial stresses.
Anyway, here’s the growth of my Future Fund over the years. 2026 shows the amount as at end May 2026:
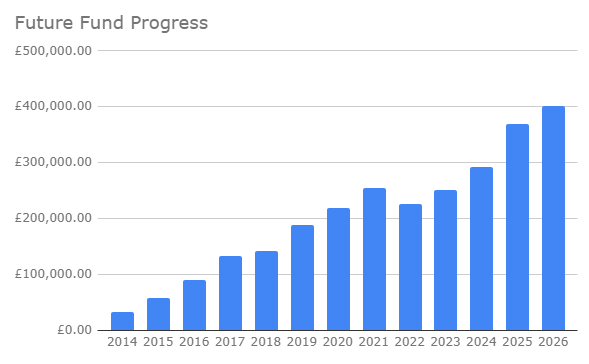
Whilst it would be nice for my FF to reach half a million, it’s not necessary for my plan.
As a reminder, my Future Fund includes my ISAs, SIPPs, Premium Bonds and my company DC pension. It is not a net worth figure and does not include any property I own, my DB pension or emergency funds.
The blip in 2022 was after I raided my Future Fund for my house deposit, but otherwise, pretty steady year-on-year progress.
How Long until I FIRE?
I make it only 17 more months of working but I only just worked this out as I’m not counting down, not yet!
Why not?
Because I need to stay fully engaged and focused with my work. Already, I occasionally feel that my mind is starting to get a little frayed around the edges work-wise, but I’m not letting it go much further than that, I can’t allow that to happen as it’s still too early to think ‘I really can’t be bothered with that!’
Pre-HRT, I didn’t realise how much I was struggling mentally with my work – I’m of a generation where I just got on with things and powered through. Now I’m on HRT, I have felt less stress but despite getting better quality sleep, just plain old age has meant that it takes so much more effort to mentally juggle, multi-task and work to fast deadlines. My brain gets so tired and exhausted, I really need the weekend to recharge and often, come Monday, I am still mentally tired.
Anyway, here are my last documented thoughts on decumulation. There have been a couple of changes since then, nothing major but I will do an updated post.
I had been aiming for an income of a moderate single person as cited by Retirement Living Standards, which had been £31,700 but which was recently updated to £32,700! I checked my spreadsheet but this increase shouldn’t derail my FIRE plan.
It’s unlikely that there will be a change in my living situation in the near future and my job is as stable as it can be. In fact, the best thing I could hope for is if they made me redundant but that is unlikely to happen. My job might be replaced by AI in the future but I will be replaced by an actual young person!
Thank You Again
Readers have come and gone over the years and I’m eternally grateful to the ones who have stuck around and who continue to support my quest for FIRE.
So as always, a massive ‘Thank You’ to all who take the time to read this little blog – I really do appreciate your comments and emails and have loved (and continue to love) sharing my journey with you all.
Thank you very much for helping me keep my focus, keeping me motivated, giving me ideas and helping me stick to my plan!
Being part of the FIRE community has meant that I have made some great friends, through online and face-to-face FIRE pub meet ups and through online investing meet ups. Thanks to Matt, Gez and Danny for your guidance on investing and thanks also to the chaps at Monevator who helped (and continue to help) me become the cautiously optimistic investor I now am (for better or worse, haha!) and for the fab post-FIRE/decumulation posts which I need to pay more attention to!
And that’s it.
Next year should be my final pre-FIRE anniversary and the anniversary after that? Well that should be my first post-FIRE anniversary!
Onwards and upwards, everybody!
We found that, in the early years of retirement, it was worth having a “flexible” mortgage. That is to say, we could overpay some capital and then, if it suited us, borrow it back again.
If such things are still available you might like to consider one.
Thanks dearieme. Not something I had thought even possible so something to consider if needed.
A bit late to this, but well done, and keep going for the final lap! Always enjoy reading your blog.
Cheers Martin!
Well done.
I still prefer written blogs to vlogs.
So keep it up please !
Thanks kwaker!
The ~17 months between now and FIRE will fly by so make sure you’ve got all the important items nailed down as best as you can ahead of time.
Having said that, i’m 3+ years into early retirement and i’m still reviewing and tweaking my drawdown plans, which i continue to find fiendishly difficult and complex. But at the same time, a good workout for the old brain cells and something that i do enjoy. For me it remains important to keep as many big financial options open for as long as possible (eg not accessing the DC pension until i was absolutely certain that i didn’t wish to return to work and contribute further to the pension pot; not purchasing an annuity at the outset, but rather delaying until later life when financial simplicity will be welcomed).
Stress testing the retirement pot….eg what will i do if the market crashes by say 50% a week after i retire?! Having a Plan B and C there just in case will help with guaranteeing the 8 hours sleep each night.
For the DC pension, and specifically the 25% tax free lump sum element, i’d be looking at whether there is any way to increase contributions over the next 17 months, thus reducing your income tax and national insurance, and bolstering the tax free lump sum. Certainly premium bonds and emergency funds could be re-routed (temporarily) in this direction to take advantage of the tax savings, and it might even make sense to live off your ISA for the next 17 months and plough your entire work income into the DC pot 100% tax free. Worth considering.
I’m due to access my final salary DB pension around the same time as you FIRE, so exciting times for both of us. Obviously maximising the benefit from the DB pension can be quite important, so make sure you optimise the timing and manner in how you access this valuable asset.
Something i didn’t take care of when i was still working was to set myself up with a second credit card, and build up the credit limit (just in case it’s ever needed in an emergency). When you stop working the world of finance can treat the asset rich but income poor like a leper, so definitely make sure you’ve got the credit card(s) positioned where you want them and get the limits as high as desired. My high street bank (been with them for 40+ years!) has been abysmal in this regard – there’s absolutely no human side to them anymore (come back please Mr Mainwaring!), and when you need their help you come up against the ‘computer says no’ response!
Hi KC
The time is indeed flying by and I am fully aware that I need to get all the important stuff done ahead of time.
I know for a fact that my ‘job’ after I finish FT work will be to be tweaking and managing my investments so am not surprised that you are still working on yours! Good to hear that it is a workout you enjoy doing!
I know I’m not going to buy an annuity until much later, but I hadn’t thought about delaying taking the DC pension, or tapping into my SIPPs in case I needed to return to work. I’m not sure I have enough in my ISAs to do that.
I’m somewhat at odds with ploughing everything into my DC/SIPPs as I feel that I am really low on the cash front. One option might be to add more to my SIPPs and not invest the money, just leave as cash in the account, whilst getting the tax relief.
Great to hear that you will be tapping into your DB pension – I think I would be excited too it’s quite a few years before it’s time for me.
On the credit card front, I have a few cards at my disposal so will be ok in that respect.
Thanks as always for you detailed comments and insights!
Hey Weenie!
I’m so glad to hear you have finally set a firm date 🙂
That’s when it really became ‘real’ for me, no more dithering/adjusting plans – the change in thinking into more of a ‘what will I do if’ type mode. Dealing with any issues rather than taking he safe option of delaying. On that note – be ready for your brain to scream at you not to disturb your routine! Though agreed, HRT defn a help
The only other ‘advice’ that I’d offer, not that you need it, is to remember to take the time to enjoy the countdown. It’s been a lot of work/patience to be able to do this and it can be easy to get too busy/anxious about the decumulation/money. I’ll always remember walking out the office for the last time with far more mixed emotions than expected!
Thanks for keeping blogging – you are a shining example to us less committed but still here old-style bloggers 🙂
Cheers, Michelle
Hey Michelle
Thanks for the advice, I can see myself needing reminders to enjoy the countdown (which I’m not thinking of just yet!)
This year is already flying by, but work is just so busy and a blur that it can’t be helped! I do hope I can stop briefly and take a breather!
Thanks for stopping by!
Hi Weenie,
I know that you have mentioned before that you feel you need to have a higher allocation to cash than the 3% as you get close to FIREing next year. I am in a similar position to you in terms of age, financing and timing and so I am grappling with this question too of how much cash (or low risk) assets to hold to mitigate sequence of returns risk. Will you do a post at some point on your thoughts on this? I for one would be interested.
Hi Tim
Thanks for posting and yes, I am thinking of writing such a post, which would be useful to me (to put my thoughts down) and hopefully to readers like yourself.
I have made some changes in the past few months, taking some profits from these all time highs and not investing that money. So it’s a little more than 3% now but where to stop? Not quite pinned on a number I’m entirely comfortable with just yet!