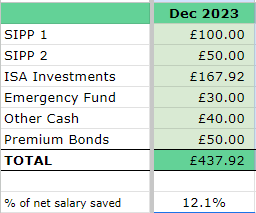
As mentioned in my last post and as highly recommended by various commenters, I’ve been tracking all my spending.
January was what I expected, but partway through February, I realised that there was definitely going to be variance between what I think I spend and what I actually spend.
It appears that lifestyle creep has happened, despite my efforts!
While I’ve been pretty good at buttoning down my household bills and differentiating between ‘need’ and ‘want’ purchases, I’ve not been so great with “social expenses”. Lunches, coffees, a swift pint after work (when I’m in the office) with friends and colleagues all add up – I didn’t even think I was that active socially but obviously enough so that these costs need looking at!
A big one will likely be gifts for friends and family – some expenses have been tracked (with receipts, credit card statements), but for some reason, I seem to have glossed over the various gifts of money (for birthdays, Christmas, Chinese New Year) to my family (and I have a big family). I’ve probably lost sight of them due to the transactions just being a bank transfer here and there, probably not helped by me actively using different current accounts simultaneously. Anyway, I’ll see what the damage is by the end of the year and hope I’m not in for too much of a shock!
February’s payslip brought a nice surprise with a bonus payment for my part in completing that project I was on. I’d forgotten about it as I had other more important things on my mind and my eligibility for it had come while I was battling with long hours and intense work activity so it wasn’t on the forefront of my mind.
I split the bonus across my ISA, SIPP, mortgage overpayment and emergency funds.
A bit left over I used to buy some small items I’d wanted (not needed 🙂 ) for my garden and kitchen.
So how did that bumper pay make my numbers look for February?
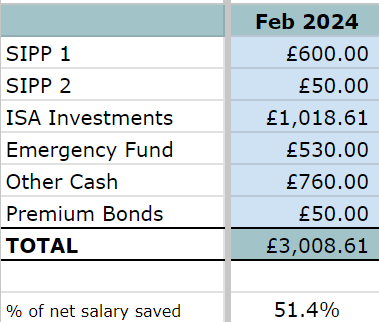
Obviously, this is way, way above my usual (much more modest) amount, but I saved 51.4% of my net salary. It’s a one-off! The above includes £63.61 from doing Prolific surveys and a £5 charity lotto win.
Shares and Investment Trusts
I finally sold my holding in Persimmon (PSN), one of the stocks I’d kept after running my Dogs of the FTSE experiment. I used the money to increase my holding in a (fairly) new holding in MP Evans Group plc (MPE), a ‘sustainable’ stock I’d dipped my toe in with a few quid last year, but which I will add to now as part of my income paying portfolio.
Other than that, no new investments, I just topped up existing ones.
Current share/IT portfolio can be found here.
(Entire portfolio here)
I need to do an update on my investing strategy but been too distracted.
Future Fund
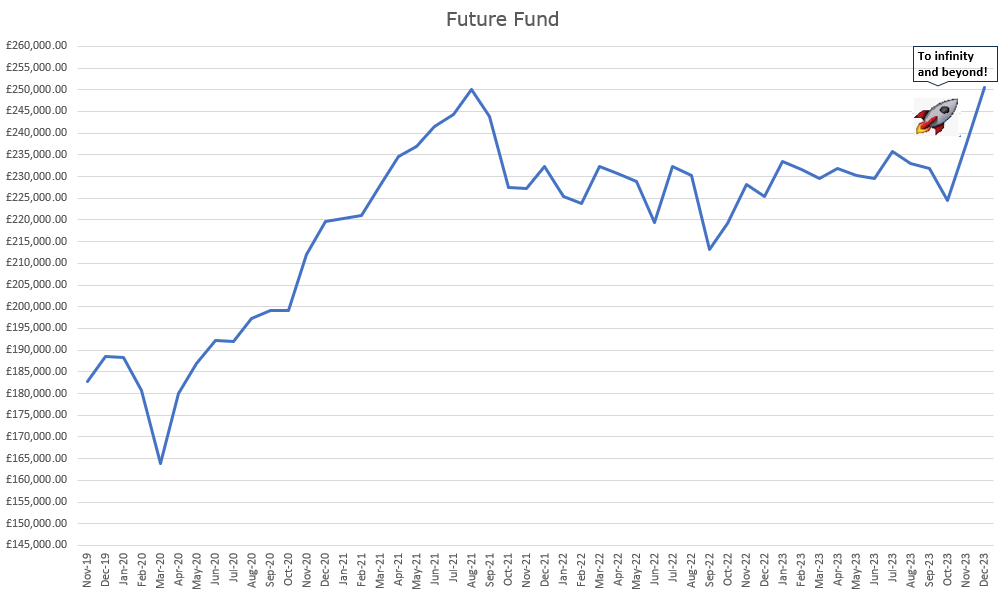
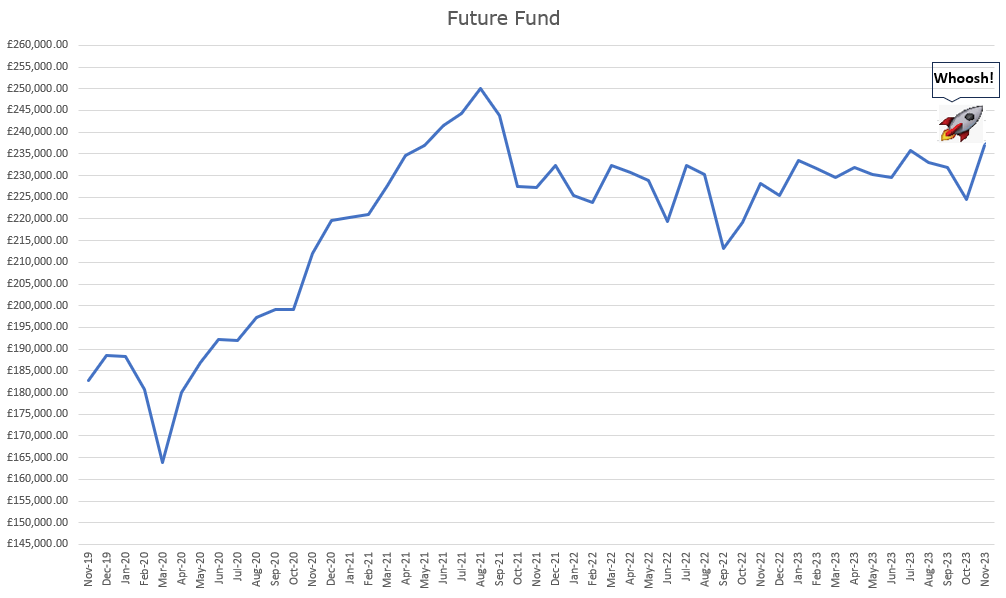
There was an uptick in the markets but admittedly, the rocket is only really there courtesy of my bumper capital injection this month. As at the end of Feb, my Future Fund stood at £253,452.87.

Dividends and Other Income
An average month for dividends: